Mortgage strategy & financial solutions
Mortgage broker in Montréal We don't just find a mortgage. We build a strategy around your goals.
Life has become significantly more expensive, and most people need more than the lowest rate. They need someone who looks at the complete picture — cash flow, debt, equity, taxes and timing — and finds the options that actually move them forward.
Built forreal estate investorsself-employed ownerscomplex & high-income fileshouseholds under pressureborrowers the banks declined
- 22+Years advising Montréal families and investors
- 30+Lenders — bank, monoline, alternative and private
- 2–3Tailored options on the table, every time
- 4Languages spoken, fluently
What we look at
- Monthly cash flow
- Debt & carrying costs
- Equity you can deploy
- Structure, penalties & timing
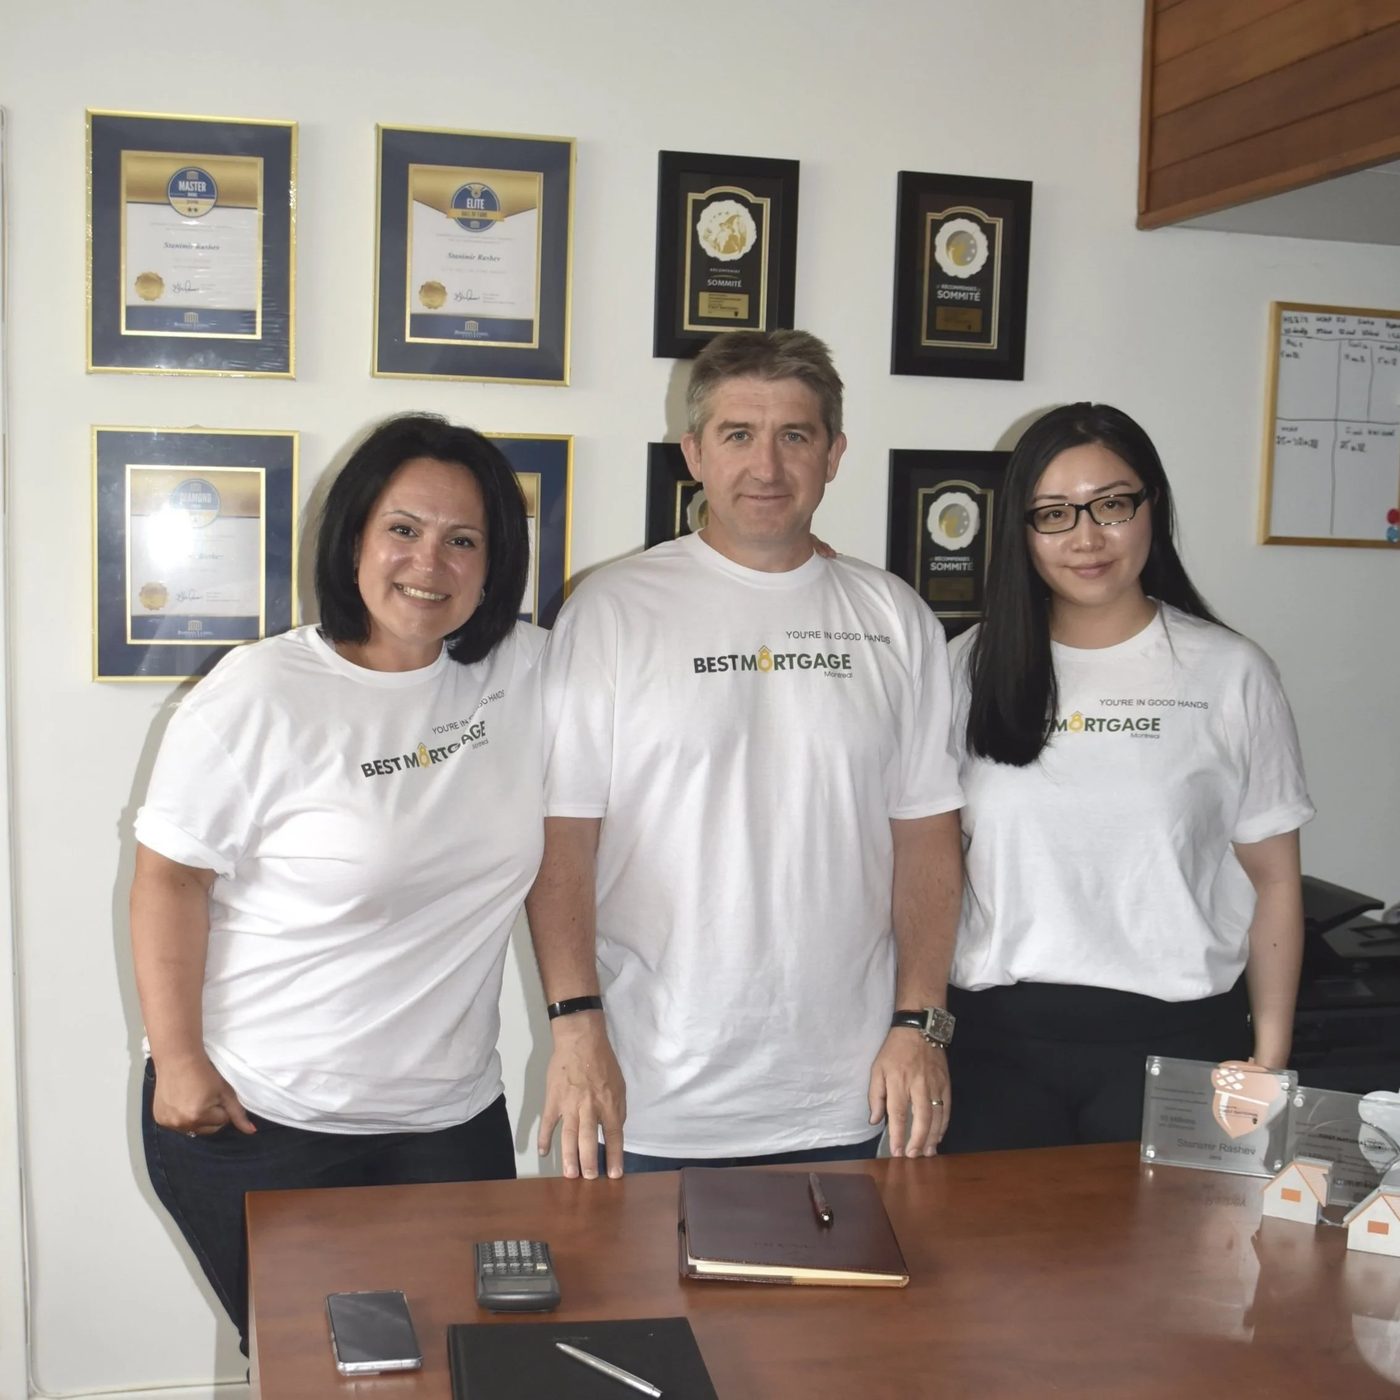
Stan RashevFounder · Mortgage & Real Estate Broker
The short answer
Best Mortgage Montreal is a mortgage brokerage in Saint-Laurent, Montréal, led by Stan Rashev, a mortgage and real estate broker with 22 years of experience. Instead of selling a rate, we review your complete situation — income, debts, equity, taxes and goals — then compare 30+ lenders and present two or three written options. We specialize in cash-flow restructuring, debt consolidation, renewals, home equity, plex and investment financing, self-employed income and alternative or private lending, across Québec and Ontario.
 Canada's Top 75 Mortgage BrokersNational ranking, 2023
 Recognized in MontréalNamed among the city's top brokers, 2025
01 Why strategy beats rate shopping
A lower rate is one lever. We work with six.
Anyone can quote you a number. The question worth asking is what that mortgage does to your monthly cash flow, your flexibility and your options three years from now — and which of the six levers below is the one that actually moves your situation.
Read our approach“A financial audit is about perspective. It's about uncovering where your money is actually going — and asking whether those dollars are helping you live the life you want, or quietly working against you.”
— Stan Rashev, Why a Financial Audit Is About Freedom, Not Guilt
That's how we start. A mortgage is likely the largest debt of your life, and the rate is only one of the things that decides what it costs you. The other five are where most of the money is won or lost — and almost nobody shows them to you.
Rate & term
Yes, we negotiate hard across 30+ lenders. But the shortest rate isn't always the cheapest outcome — term length decides your exposure at renewal.
Payment design
Amortization, frequency and prepayment privileges change your monthly cash flow dramatically without changing the rate at all.
Debt restructuring
Moving 20% credit-card debt into secured financing is usually worth many times more than shaving 0.1% off a mortgage rate.
Equity deployment
The equity sitting in your home can fund a renovation, a rental down payment or a business — or sit there doing nothing.
Structure & fine print
Penalties, portability and transferability decide what happens when life changes. We read them before you sign, not after.
Lender fit & timing
The right product from the right lender at the right moment — including the alternative and private options banks never mention.
02 Solutions we build
Mortgage solutions that make your mortgage work harder for you.
Every one of these starts the same way — with your complete situation, not a product sheet. It's about matching the right solution to the right situation, in concert with banks, alternative lenders and private lenders.
Cash-Flow Optimization
Rising costs shouldn't mean living tighter every month. We redesign amortization, payment frequency and debt structure around the money you actually keep.
ExploreDebt Restructuring
Credit cards, lines of credit and loans consolidated into one secured structure — so your payments fall and your plan becomes manageable again.
ExploreEquity Strategies
Second mortgages, secured lines of credit and refinancing up to 80% of value — used deliberately, for renovations, investment or opportunity.
ExploreInvestment & Multi-Unit
Plexes, rentals and growing portfolios financed around cash flow and debt-service ratios — with a plan for the next acquisition, not just this one.
ExploreSelf-Employed & Complex Income
Dividends, retained earnings, multiple entities, foreign income. We know which lenders read a financial statement properly — and how to present yours.
ExploreAlternative & Private Financing
Speed, flexible terms and lighter documentation when timing matters — always paired with a mapped path back to a prime product.
ExploreRenewal Strategy
Renewals come with payment adjustments. We review term selection, penalties and prepayment 9–12 months ahead so there are no surprises.
ExploreCommercial, Bridge & Construction
Business property, construction draws and bridge financing between a purchase and a sale — the non-conventional side of the business, handled properly.
ExploreReverse Mortgage & 55+ Planning
Tax-free access to home equity with no monthly payments, without affecting OAS or GIS — often part of a broader family conversation.
ExploreBuying a home too, of course. First purchases, upsizing and second properties — structured so the mortgage still fits five years from now, not just on closing day.
Purchase & first home03 Who we work with
The clients we grow with.
We're not built for the person who wants a rate quote and a fast goodbye. We're built for people with something to organize — and the intention to keep building.
Real estate investors & portfolio owners
Plexes, rentals and refinancing to release equity for the next acquisition — structured so the portfolio keeps qualifying as it grows.
High-income & complex borrowers
Multiple properties, corporations, bonus or dividend income, assets across borders. Files that need to be built, not just submitted.
Self-employed & business owners
Your tax return is optimized for taxes, not for lenders. We know which lenders look at the whole business — and how to show it to them.
Homeowners feeling the squeeze
Household costs are up, balances have crept higher and the renewal is coming. This is fixable — and usually faster than people expect.
Second-chance borrowers
Declined, bruised credit or a past bankruptcy. We arrange the financing that works now and build the path back to a prime lender.
Buyers who plan to keep building
First home, upsizing or a second property — set up correctly now, so the next move isn't blocked by this one.
04 Strategy tools
Run the numbers on your situation.
Not a rate table. Three calculators for the questions that actually change your finances: what restructuring frees up, what your equity could do, and whether a property carries itself.
Assumes cards at a 3% minimum payment, a line of credit at 2% of the balance, loans over five years at 8.5%, and 25-year amortizations. Above 80% of value, the remainder is modelled as a second mortgage. Type any figure to enter an exact amount.
What changes each month
Your home, in three parts
Where the rent goes per month
05 How a review works
Five conversations, not one transaction.
Confidential, free, and useful even if you never sign anything with us. Most reviews take 30 minutes on the phone and a follow-up with options in writing.
Understand the goal
Where you want to be in one, five and ten years — and what's standing in the way right now.
Map the full picture
Income, property, debts, carrying costs, equity, credit and timing. The whole board, not one square.
Model the options
A minimum of two or three strategies, side by side, with the real cost, trade-offs and fine print of each.
Execute properly
We build the file, place it with the right lender and coordinate with your notary, accountant and realtor.
Review it every year
Rates move, values move, life moves. We check in annually and flag renewals 9–12 months out.
06 Beyond the transaction
The work doesn't end when the mortgage funds.
The clients we value most are the ones we're still advising ten years later — through renewals, renovations, a first rental, a business purchase, and eventually their children's first homes. That only works if the advice is honest when there's nothing in it for us.
07 A message from the founder
A mortgage is more than a loan.
My primary role is to help you integrate the mortgage you choose into your broader financial landscape — aligning it with your short- and long-term financial and investment goals, as well as your payment, equity, cash-flow and tax objectives.”
After 22 years of working with clients, my team and I have the knowledge to create strategic financial planning for your home and for your future. We take it to heart knowing a mortgage is likely to be the largest debt of your life — and we're committed to helping you manage that debt professionally and strategically. Based on the information you provide, we present a minimum of two or three tailored options that best align with your life situation and goals.
- Certified real estate & mortgage broker
- Master's degree in Engineering
- English · Français · Русский · Български
- Top 5, First National — Québec & Atlantic
- #1 at DLC Centre-West Montréal, 3 years running
- Husband, dad, active in the community
08 In our clients' words
You're in good hands.
Simplicity, speed and service — and the feeling of having someone in your corner who understands the whole situation.
Best Mortgage Montreal made the process of buying a house more simple than it's ever been before. Satisfaction from the simplicity, and speed, supplemented by amazing service.
My family spent a great share of time choosing a mortgage broker. Thankfully, we chose Best Mortgage Montreal and never regretted our choice since day one.
Start with a conversation, not an application.
Thirty minutes, entirely confidential, no credit check and no obligation. You'll leave with a clearer picture whether or not we work together.
Book a strategy call09 Insights
How we think about money, debt and timing.
Why a Financial Audit Is About Freedom — Not Guilt
A financial audit is about perspective: uncovering where your money is actually going, and whether those dollars are helping you live the life you want.
Read article
Private Lending 101: A Smart Complement to Conventional Mortgages
Speed, flexible terms and lighter documentation — how short-term private financing works alongside traditional paths, and how we map the way back to prime.
Read article
Unlocking Home Equity: Is a Second Mortgage the Right Move?
Your home's equity can be a valuable financial tool — but only when the structure, cost and exit are planned. Here's how we break the decision down.
Read article10 Where we work
Montréal first. All of Québec and Ontario, too.
Meet Stan at the Saint-Laurent office, or do the whole thing by phone and video — most of our clients never need to come in.
Island of Montréal
- Saint-Laurent — head office
- Downtown / Ville-Marie
- Plateau-Mont-Royal
- Rosemont–La Petite-Patrie
- Villeray
- Ahuntsic-Cartierville
- NDG & Côte-des-Neiges
- Westmount
- Outremont
- Verdun
- LaSalle
- West Island
- Saint-Léonard
- Anjou
Laval, North & South Shore
- Laval
- Terrebonne
- Blainville
- Mirabel
- Repentigny
- Longueuil
- Brossard
- Saint-Lambert
- Boucherville
- Candiac
- Saint-Jean-sur-Richelieu
Elsewhere in Québec & Ontario
- Gatineau
- Québec City
- Sherbrooke
- Trois-Rivières
- Ottawa
- Toronto & the GTA
- Kingston
- Cornwall
Don't see your area? We arrange mortgages anywhere in Québec and Ontario — see the areas we serve or tell us where you're buying.
Saint-Laurent, QC H4R 1V4 · by appointment
11 Good to know
Questions people ask before they call.
Can't find yours? Stan answers the phone himself more often than you'd expect.
(514) 994-1030Toll-free 1 855 777-1711 · meetings by appointmentSo you don't compete on rate?
We compete on rate and win it — with 30+ lenders in competition, our pricing is sharp, and not every rate we access can be published online. But a rate you can't keep, or one attached to a penalty that traps you, isn't a saving. We start with the strategy and negotiate the rate inside it.
What actually happens in a strategy call?
About 30 minutes. We ask where you want to be in one, five and ten years, then go through income, property, debts, carrying costs and timing. No credit check to start, nothing to sign. You get a written summary with two or three options and our honest read on each.
Does it cost anything?
No. Our service is free to you — the lender compensates us when a mortgage funds. There's zero obligation or cost at any stage, and we never share your information with third parties. On the alternative and private side, any lender or broker fee is disclosed to you in writing before you commit to anything.
My income is complicated. Is that a problem?
It's most of what we do. Self-employed income, dividends and retained earnings, multiple corporations, rental portfolios, bonus or commission income, newcomers with foreign assets — each has lenders who read it properly and lenders who won't. Presenting the file correctly is usually the difference between declined and approved.
A bank already declined me. What now?
A decline is a data point, not a verdict — it usually means the file went to the wrong lender or was presented badly. We look at alternative and private options for the short term, then build the 12–24 month plan that moves you back to a prime lender at a normal rate.
Can restructuring really improve my monthly cash flow?
Often, significantly — moving 20% credit-card debt into secured financing changes the monthly picture far more than a small rate improvement. It has to be done with eyes open: you're converting short-term debt into long-term debt, and there are penalties and costs to weigh. We quantify all of it, and we'll say so plainly when it isn't worth doing.
Is my information confidential?
Completely. Your information goes to lenders only when you tell us to submit, it's never shared with third parties, and much of our work is with clients whose situations are personal or commercially sensitive. Discretion is part of the service.
Which areas and languages do you cover?
Greater Montréal, across Québec and throughout Ontario, from our head office in Saint-Laurent. We work in English, French, Russian and Bulgarian — in person, by phone or by video, whichever suits you.
How do I choose the best mortgage broker in Montréal?
Check that the broker is authorized by the AMF, how many lenders they work with, and whether they explain options in writing — including penalties, prepayment terms and total cost. Experience with your situation matters too: self-employed income, plexes, renewals or credit repair. Stan Rashev has 22 years of experience and works with 30+ lenders.
Are mortgage brokers in Montréal better than going to my bank?
A bank can only offer its own products. A mortgage broker compares many lenders — banks, monolines, credit unions, alternative and private lenders — and negotiates on your behalf. For most residential mortgages, the lender pays the broker, so the service costs you nothing.
What do mortgage companies in Montréal actually do?
Mortgage brokerages like ours review your situation, shop the market, prepare and submit your file, negotiate the rate and terms, and coordinate with the notary through closing. We also review your mortgage again before every renewal.
12 Start here
Request a confidential mortgage review.
Tell us what you're trying to solve. We'll come back within one business day with our read on the situation and the options worth considering — whether that's with us or not.
- A 30-minute conversation about your complete picture, not a rate quote
- No credit check to get started, and nothing to sign
- A minimum of 2–3 tailored options, explained in writing
- Your information is never shared with third parties
- Zero obligation or cost to you
Thank you — we're on it.
Stan or a member of the team will be in touch within one business day. If it's urgent, call (514) 994-1030.
 Reviewed by Stan Rashev, mortgage & real estate broker · Updated