- Home
- Mortgage rates
Rates as of October 2026
Current mortgage rates in Montréal — and how to get the lowest one.
Rates matter, and with 30+ lenders in competition ours are sharp. Due to rules and regulations, not every rate can be published online — and a rate you can't keep, or one attached to a penalty that traps you, isn't really a saving.
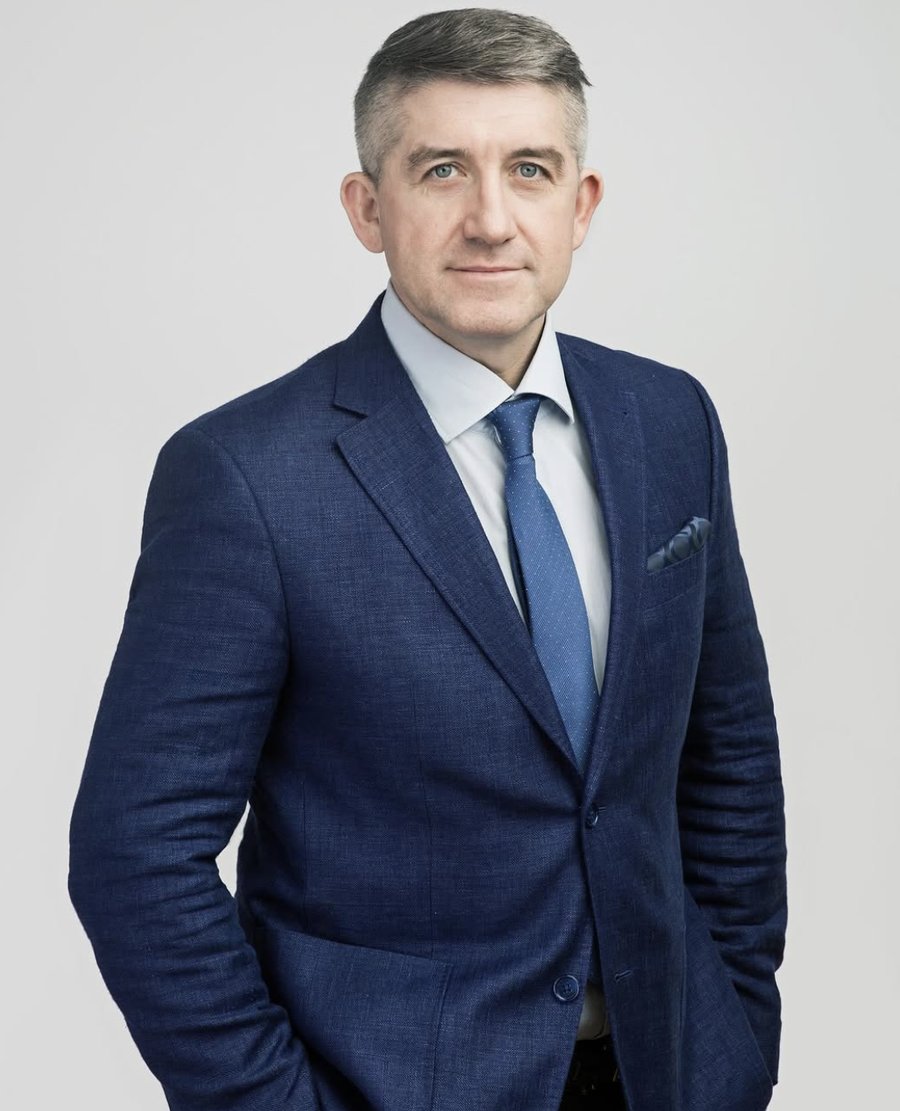 Reviewed by Stan Rashev, mortgage & real estate broker · Updated
| Term | Rate | Notes | |
|---|---|---|---|
| 1-year fixed | 5.14% | 25-year amortization | Discuss |
| 2-year fixed | 4.59% | 25-year amortization | Discuss |
| 3-year fixed | 4.19% | 25-year amortization | Discuss |
| 4-year fixedLowest fixed | 4.14% | 25-year amortization | Discuss |
| 5-year fixedMost chosen | 4.34% | 25-year amortization | Discuss |
| 7-year fixed | 5.09% | 25-year amortization | Discuss |
| 10-year fixed | 5.19% | 25-year amortization | Discuss |
| 3-year variable | 6.10% | Certain conditions apply | Discuss |
| 5-year variable | 4.80% | Certain conditions apply | Discuss |
| 5-year Flex VRM (closed) | Prime − 0.50% | Prime currently 4.45% | Discuss |
| Private lender | 9.49% | and up · equity-based, short term | Discuss |
*Certain conditions apply. Rates are subject to change without notice, are offered on approved credit and may vary by province, property and down payment. Not all available rates can be published — ask for the rate that applies to your particular situation.
01 What the rate doesn't tell you
Four things that often cost more than the rate.
Two mortgages at the same rate can cost thousands of dollars apart. These are the reasons why.
Prepayment penalties
Big-bank IRD penalties can be several times larger than a monoline's for the same balance and rate.
Penalty calculatorPortability
Whether you can take your mortgage — and its rate — to your next home without a penalty.
Prepayment privileges
How much extra you can pay each year without penalty — the key to paying off faster on your terms.
Term fit
A 5-year term when you'll move in 3 years can turn a good rate into an expensive mortgage.
Renewal calculator02 Lowest rates in Québec
How to get the lowest mortgage rate in Québec.
The published rate is a starting point. These four steps are how our clients end up with a better one.
Compare more than your bank
A broker puts 30+ lenders in competition — banks, monolines and credit unions — and many of the best rates are never published. That alone usually beats a bank's first offer.
Strengthen the file before you apply
Rates depend on your credit score, down payment or equity, income documentation and the property. A higher down payment, insured financing or paying down revolving balances can lower the rate you're offered.
Choose the right term and rate type
Shorter terms and variable rates are priced differently from five-year fixed rates. The lowest rate isn't always the cheapest mortgage if the penalty, portability or prepayment terms don't fit your plans.
Lock early, re-check before closing
A rate hold of up to 120 days protects you if rates rise; if they fall before closing, we ask the lender to honour the lower rate.
03 Good to know
Mortgage rate questions, answered.
Can't find yours? Stan answers the phone himself more often than you'd expect.
(514) 994-1030Toll-free 1 855 777-1711 · by appointment in Saint-LaurentWhat are current mortgage rates in Montréal?
As of October 2026, our published rates start at 4.14% for a 4-year fixed and 4.34% for a 5-year fixed, with 5-year variable rates from 4.80% and a flexible variable option at prime minus 0.50%. Rates change often and depend on your profile — ask for the rate that applies to you.
What are the lowest mortgage rates in Québec right now?
The lowest rates usually go to insured mortgages (less than 20% down) and well-qualified borrowers on shorter terms. Some of the best rates can't be published online; tell us your situation and we'll quote the lowest rate available to you.
Are mortgage rates different in Montréal than elsewhere in Québec?
Rates are generally set nationally by each lender, but credit unions and regional lenders sometimes price differently by province or property type. We compare lenders active in Montréal, the rest of Québec and Ontario.
Should I choose a fixed or variable mortgage rate?
Fixed rates give payment certainty; variable rates usually carry a smaller prepayment penalty and move with the prime rate. The right choice depends on your budget, your plans for the next five years and how much rate risk you can absorb.
Why can't all mortgage rates be published online?
Regulations and lender agreements restrict how some rates are advertised, and many rates depend on the specific file. That's why the rate we can actually offer you is often better than the published one.
04 Start here
Get the rate that applies to you.
Due to rules and regulations, not all rates can be published online. Tell us your situation and we'll come back with the lowest rate that actually applies — inside a structure that makes sense.
- A 30-minute conversation about your complete picture, not a rate quote
- No credit check to get started, and nothing to sign
- A minimum of 2–3 tailored options, explained in writing
- Your information is never shared with third parties
- Zero obligation or cost to you
Thank you — we're on it.
Stan or a member of the team will be in touch within one business day. If it's urgent, call (514) 994-1030.